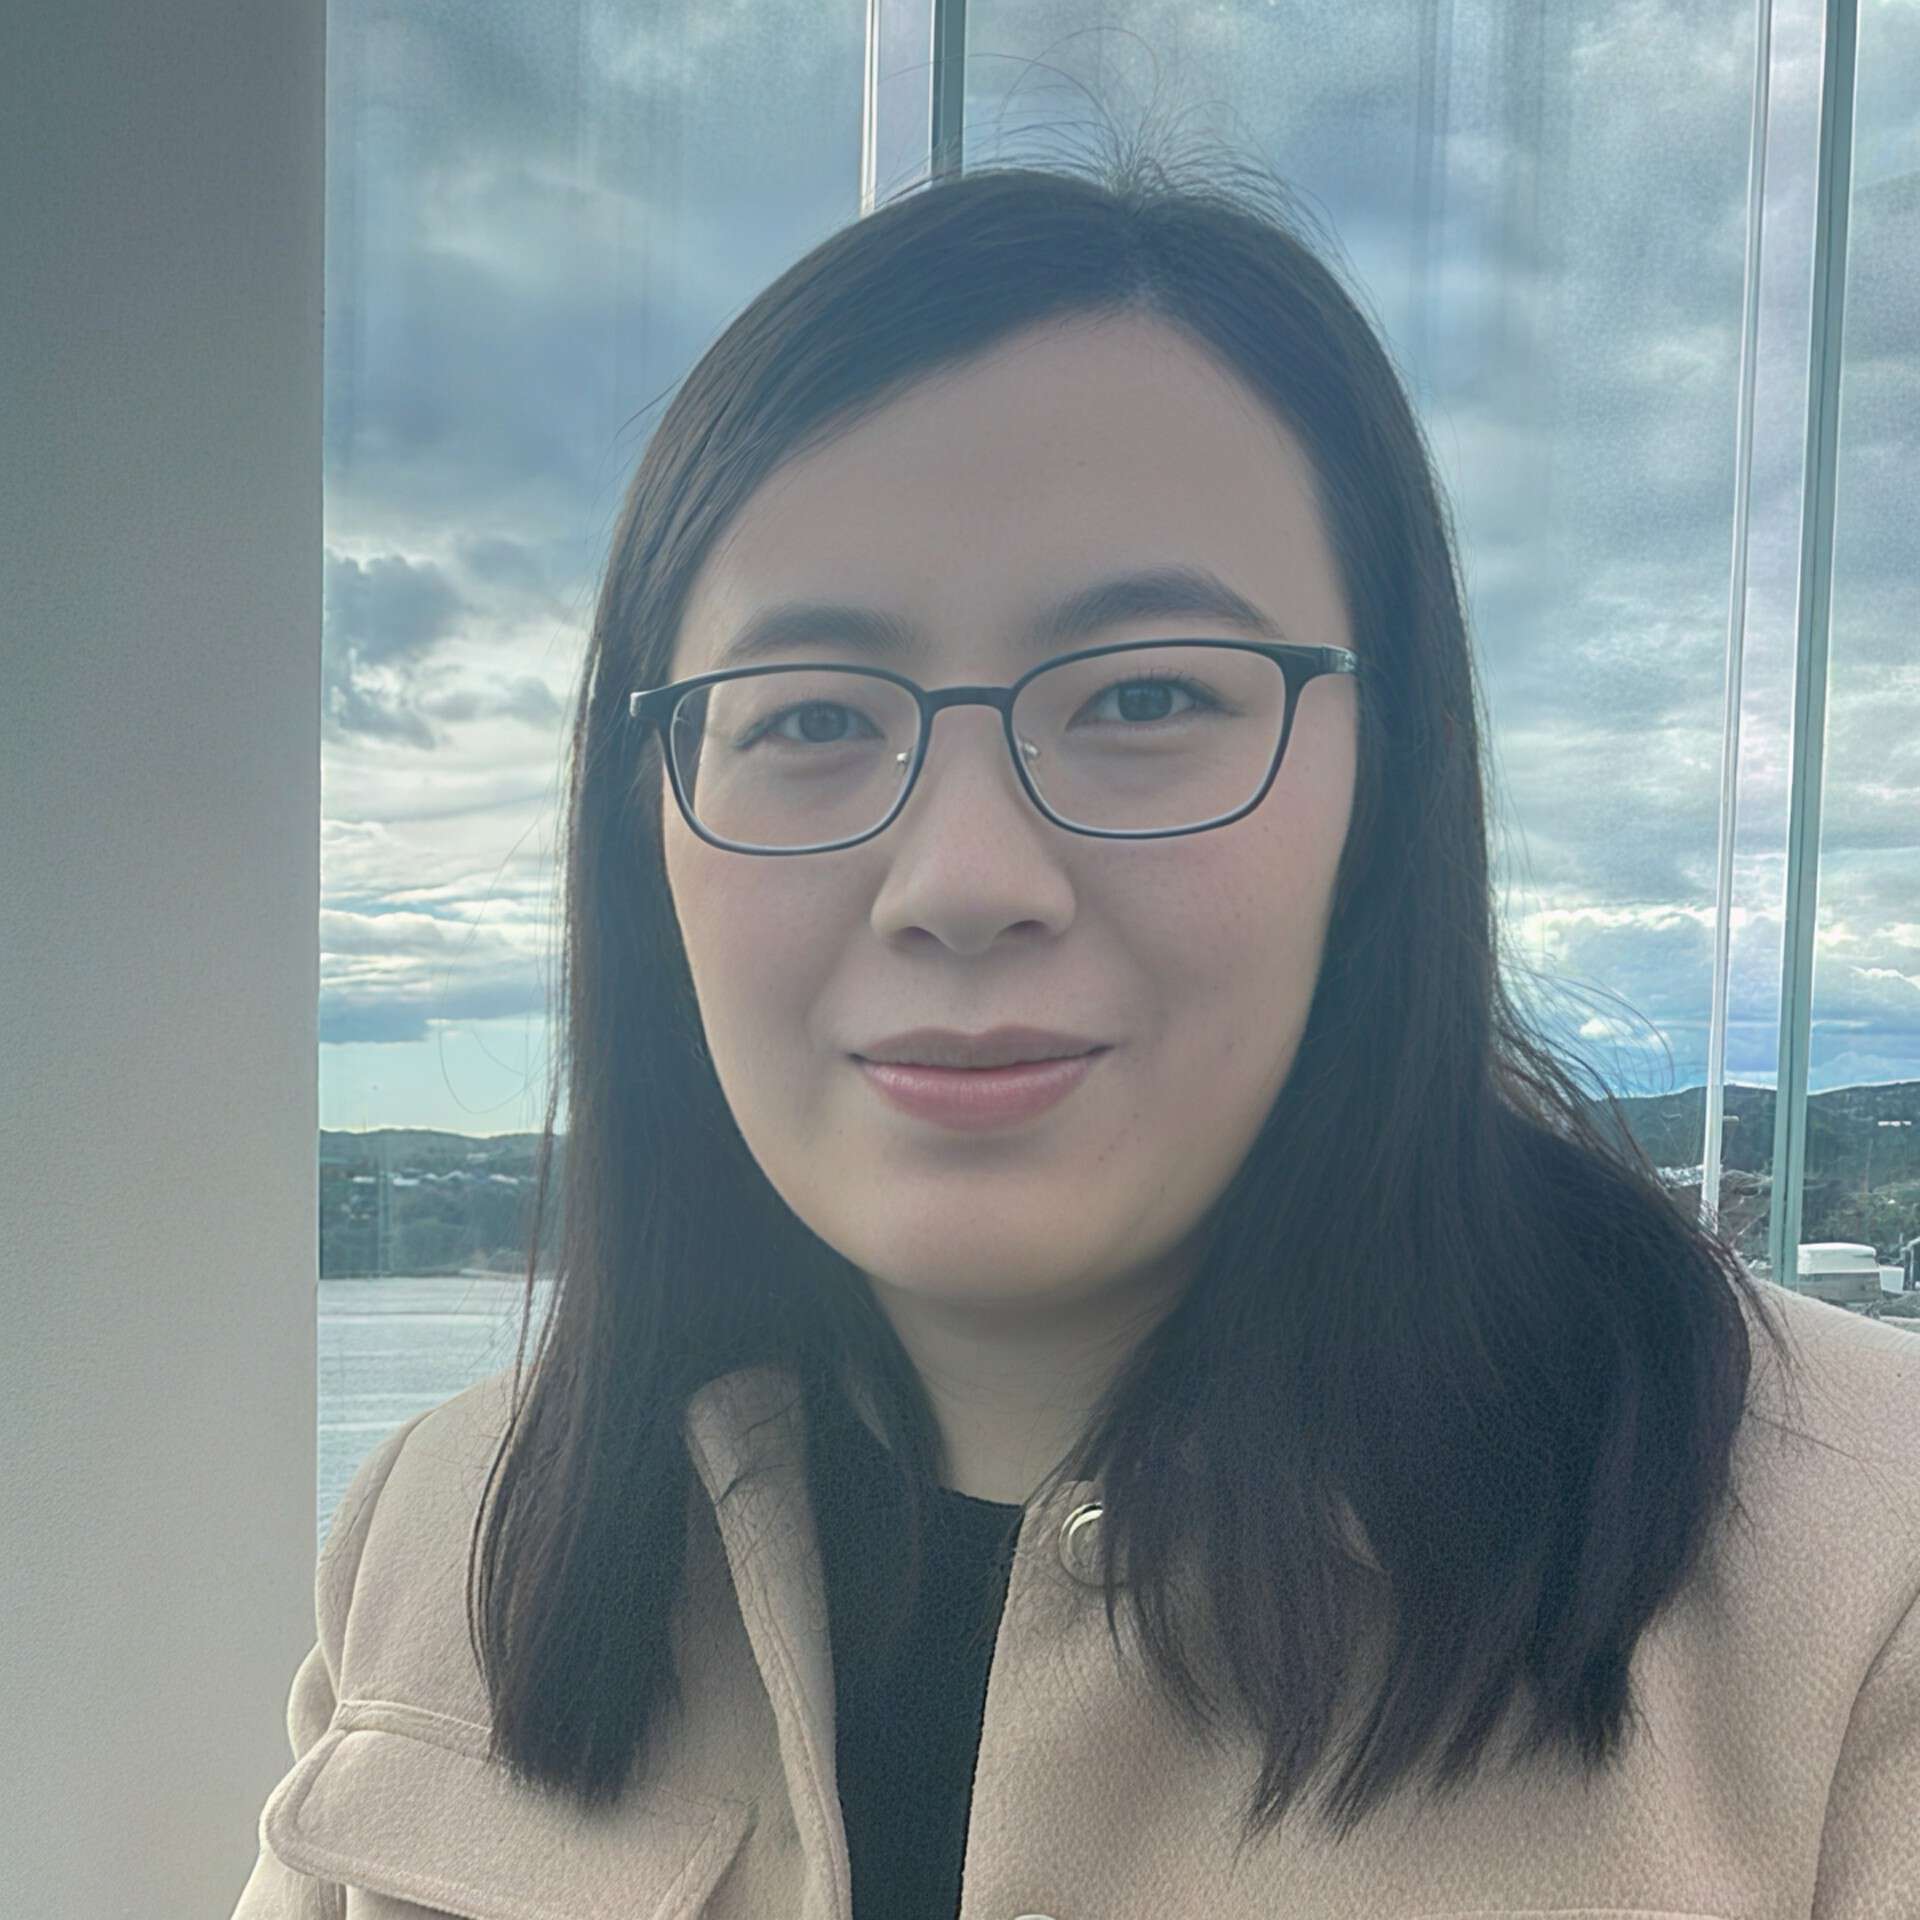
- Trial lecture starts at 10.15
- Public defence starts at 12.00
The title of the trial lecture is "What is the rationale for regulating digital consumer lending, and which public policy measures are most appropriate? Furthermore, how can your researchcontribute to public understanding and inform policy debates on digital consumer lending in a Nordic context?"
Assessment committee:
- Head of committee: Professor Trond Randøy, UiA
- Professor Ramona Rupeika-Apoga, Universitetet i Latvia
- Professor Sunghan Ryu, Nottingham University Ningbo China
Supervisors in the doctoral work:
- Professor Rotem Shneor
Summary of thesis
The objective of this dissertation is to explore the post-adoption behavior of digital consumer lending. As digital lending platforms become increasingly prevalent and continue to reshape the evolving financial landscape, lenders and policymakers must understand how alternative finance influences individual decision-making. The primary question that this research seeks to answer is: What factors influence spending behavior and repayment patterns among borrowers in the context of digital consumer lending? Particular emphasis has been placed on such dimensions as technology acceptance, credit risk, experiential learning, and customer satisfaction.
The dissertation comprises three articles: one literature review (Study 1) and two empirical studies (Studies 2 and 3). Study 1 undertakes a comprehensive review of credit risk management in peer-to-peer lending, a prevailing form of digital lending. It reveals a prominent methodological trend toward ensemble modeling techniques and advanced algorithms and it highlights the theoretical and empirical insufficiency of existing studies.
Building on this, Study 2 examines post-adoption behavior based on data collected from users of a digital lending platform in the Philippines. Study 2 is concerned with the antecedents of borrowing amount by leveraging major constructs of the Technology Acceptance Model (TAM) (Davis, 1989). In addition, incorporating the credit risk (Golden & Walker, 1997; Strischek, 2017) and experiential learning (Ellis et al., 2006; Kolb et al., 2014) theories enabled the adaption of borrowers’ risk profiles and financing experiences to construct an extended TAM framework.
In Study 3, the research context shifts to another form of digital finance: the buy now, pay later (BNPL) model. Complementing Study 2, Study 3 provides a comparative analysis of two-dimensional spending behavior among BNPL users. An extended TAM framework is developed by introducing an impulse buying framework (Xiao & Nicholson, 2013) and Expectation-Confirmation Theory (Oliver, 1980), with the aim of illuminating variations in spending habits across cultures, informing both lending strategies and credit risk assessment.
Collectively, these studies contribute to a deeper understanding of post-adoption borrower behavior in digital lending markets, contrasting with the majority of the literature in this area, which focuses on pre-adoption engagement. Firstly, the dissertation traces consumer behavior of digital lending back to credit risk, behavioral, and affective layers beyond TAM. Secondly, it clarifies supply-side strategies across marketing, customer service, and risk management. Thirdly, the generalizability of the research findings across cultures is explored, underscoring the dissertation’s attention to distinct credit infrastructures across economies
What to do as an online audience member
The disputation is open to the public. To follow the trial lecture and the public defence online, register on Zoom.
We ask online audience members to join no earlier than 10 minutes in advance. After these times, you can leave and rejoin the meeting at any time.
Opponent ex auditorio:
Deadline for the public to pose questions is during the break between the two opponents. Questions ex auditorio can be submitted to disputation chair.
Questions?

- gunvor.guttormsen@uia.no
- Phone
- +47 38 14 16 48